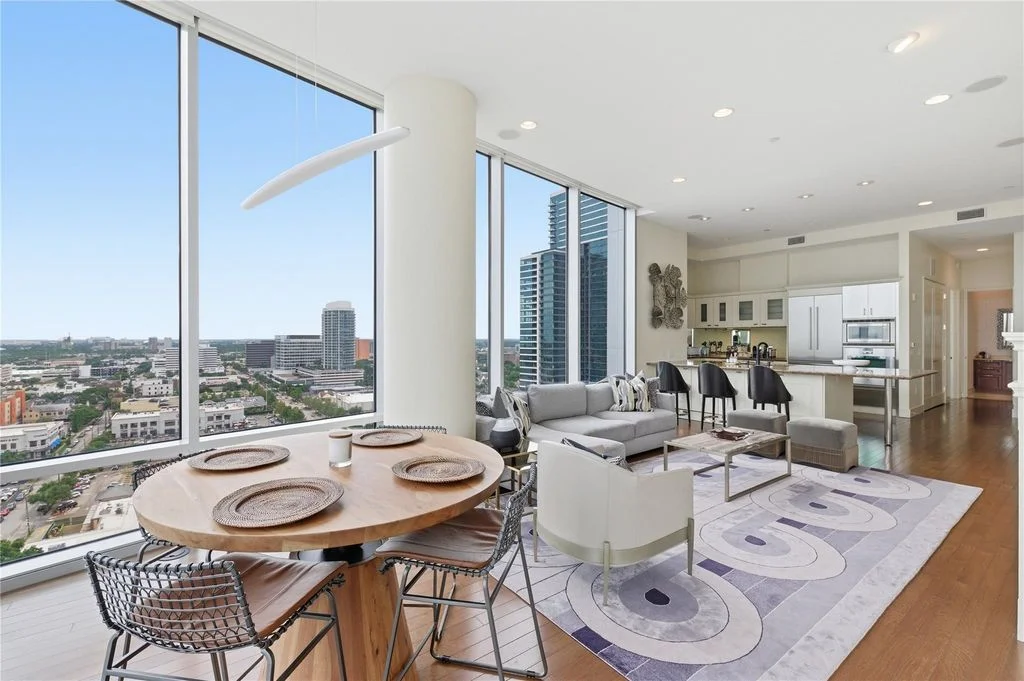
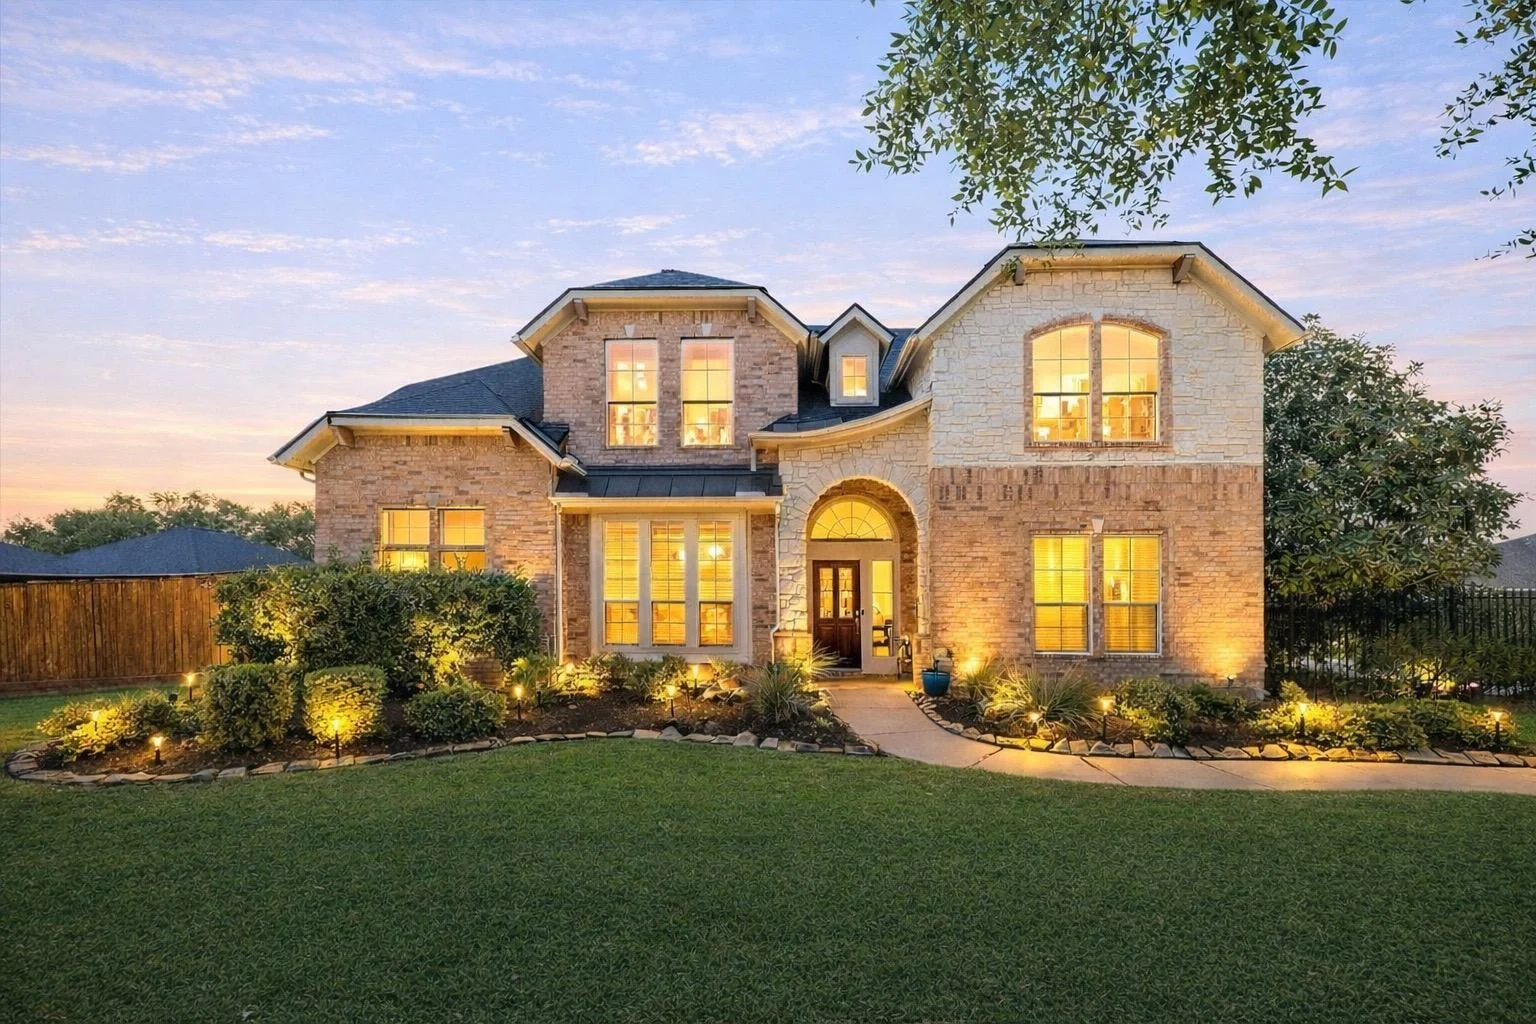
Pros and Cons of Renting vs Buying
Explore the pros and cons of renting vs. buying a home to determine which option fits your financial goals and lifestyle best.
Deciding between renting and buying a home is a significant choice that impacts your finances, lifestyle, and plans. Both options have pros and cons, which makes the decision highly personal. To make the best choice, it’s important to align your housing decision with your financial situation, lifestyle preferences, and long-term goals. Let’s break it down.
Key Takeaways
- Renting vs. buying is a significant decision that depends on your financial situation, lifestyle, and long-term goals.
- Renting offers flexibility, making it ideal for those who may relocate frequently for work or personal reasons.
- Lower initial costs make renting an accessible option, as it usually only requires a deposit and the first month’s rent.
- Renting vs. buying calculator tools can help assess the cost differences based on your current financial position.
- Renting vs. buying calculator tools allow prospective buyers and renters to compare long-term financial impacts.
Renting: The Flexible Option
Renting offers mobility, fewer upfront costs, and fewer responsibilities compared to buying. It’s the right choice for many, depending on their current life stage and priorities.
For renters who want help understanding their options and navigating the Houston housing market, exploring our Houston real estate services can provide additional guidance.
Pros of Renting
Flexibility
Renting offers flexibility to relocate without the long-term commitment of owning a home. With leases usually lasting a year, you can easily adapt to changes in your job or personal life.
Example: Suppose you’re a young professional starting your career. You may need to move to different cities to explore better job opportunities. Renting allows you to pack up and leave with minimal hassle compared to selling a house.
Lower Initial Costs
When renting, your upfront expenses are typically limited to a security deposit and the first month’s rent. These costs are significantly lower than the down payment, closing, and home-buying fees.
Example: If you’re looking at a $300,000 home, you might need $60,000 for a down payment and closing costs. In contrast, renting a $1,500/month apartment usually requires a $1,500 deposit and the first month’s rent, totaling $3,000.
No Maintenance Responsibility
As a renter, you aren’t responsible for repairs and maintenance. If something breaks, you call your landlord. This benefit saves you time and money.
Example: Imagine your apartment’s water heater breaks down. As a renter, the landlord covers the repair costs. Homeowners, however, could face a bill ranging from $500 to $1,000 to replace it.
Access to Amenities
Many rental properties offer amenities like pools, gyms, and shared outdoor spaces. Renters often enjoy these perks without additional fees or maintenance responsibilities.
Example: If you rent an apartment in a complex with a gym, you may save on a gym membership. Homeowners who want a similar setup often must invest in equipment or pay for construction costs.
Predictable Expenses
Rent is typically a fixed amount in your lease, making it easier to budget. While rents can increase, you’ll know the amount for your lease term.
Example: If you sign a one-year lease for $1,200/month, you know exactly how much to set aside for monthly housing. Homeowners face fluctuating costs from property taxes, insurance, and unexpected repairs.
Cons of Renting
No Equity Building
Renting does not allow you to build equity or ownership. Your monthly rent payments contribute to your landlord’s wealth, not yours.
Example: After five years of paying $1,200/month in rent, you would have spent $72,000 without owning anything. Conversely, the same money applied to a mortgage would reduce your loan balance.
Limited Customization
Landlords often restrict changes you can make to the property. For example, painting walls, installing fixtures, or renovating may not be allowed.
Example: If you want to install custom shelving in your rented apartment, you may need to leave it as-is when you move out, forfeiting your investment.
Rent Increases
Landlords have the right to raise rent, sometimes significantly. This lack of control can make renting less predictable in the long run.
Example: You might move into an apartment for $1,000/month. However, if rents in the area rise, your landlord could increase your rent to $1,200/month upon lease renewal.
Lack of Stability
Renting doesn’t guarantee long-term housing. You may have to move if a landlord sells or uses the property for other purposes.
Example: Imagine renting a home for three years. If your landlord sells the property, you must find a new place, often on short notice.
No Tax Benefits
Renters don’t receive the tax deductions that homeowners enjoy, such as those for mortgage interest and property taxes.
Example: If a homeowner pays $10,000 in mortgage interest in a year, they can deduct this from their taxable income. Renters receive no comparable benefit.
Buying: The Path to Ownership
Buying a home offers stability, equity-building, and the freedom to own a house. However, it requires significant upfront costs and comes with ongoing responsibilities.
If you’re considering buying and want to understand the different options available, our real estate services can help you make a more informed decision based on your goals and circumstances.
Pros of Buying
Equity Building
When you buy, your monthly mortgage payments build ownership over time. As you repay your loan, you accumulate equity—a financial asset.
Example: If you buy a $300,000 home and pay $1,500/month toward your mortgage, a portion of every payment goes toward reducing your loan balance. After five years, you might have $50,000 in equity.
Stability
Homeownership offers long-term housing stability, especially for those who want to stay in one location.
Example: Owning a home means you don’t have to worry about a landlord selling the property or raising the rent. You control your living situation.
Customization Freedom
As a homeowner, you can make any changes to your home that align with your vision, from painting walls to adding rooms.
Example: Want to renovate your kitchen? As a homeowner, you can create your dream design without permission.
Potential Tax Benefits
Homeowners can qualify for deductions on mortgage interest and property taxes, reducing their tax burden.
Example: If you pay $15,000 in mortgage interest and property taxes, you may deduct that amount from your taxable income, potentially saving thousands.
Appreciation Potential
Over time, real estate values tend to increase, allowing homeowners to sell at a profit.
Example: A $300,000 home purchased today might be worth $350,000 in five years, providing a $50,000 return on investment if sold.
Cons of Buying
High Initial Costs
The upfront costs of buying a home include a down payment, closing costs, and fees, which can add up quickly.
Example: For a $300,000 home, a 20% down payment ($60,000) and additional closing costs ($5,000–$10,000) make the upfront expense significant.
Maintenance and Repairs
Homeowners handle all maintenance and repairs, which can be costly and time-consuming. That’s where a renting vs. buying calculator can come in handy, letting you know the total cost.
Example: Replacing a roof can cost between $8,000 and $15,000—a responsibility renters never face.
Less Flexibility
Selling a home can take months, making it harder to relocate quickly.
Example: If a new job opportunity arises across the country, you might need to rent out your home or sell it before moving.
Market Risk
Home values can decline, potentially leading to financial loss if you sell during a downturn. That’s why check the renting vs. buying calculator before deciding whether to rent or buy.
Example: If your $300,000 home decreases in value to $250,000, selling could result in a $50,000 loss.
Additional Expenses
Homeownership involves ongoing costs like property taxes, insurance, and potential HOA fees. You can use a renting vs. buying calculator to compare the cost of both options.
Example: In some neighborhoods, HOA fees can range from $100 to $400/month, adding to your housing expenses.
Key Considerations
Various factors affect whether to rent or buy, some of which may require you to use a renting vs. buying calculator.
Financial Situation
Evaluate your income, savings, and ability to afford a down payment or rent increases. A renting vs. buying calculator can help compare costs based on your circumstances.
Lifestyle Preferences
Apart from considering the renting vs. buying calculator, consider flexibility and mobility. Renting suits those who move often, while buying suits those who prefer long-term stability.
Long-Term Goals
Think about your priorities and keep an eye on the renting vs. buying calculator. If building equity and wealth matters most, buying might be better. Renting is ideal for those focused on short-term convenience.
Conclusion
The choice between renting vs. buying ultimately depends on your unique situation. Both options have advantages and drawbacks that align differently with financial, lifestyle, and long-term goals. Understanding your options and working with someone familiar with the Houston market can make the decision easier.
If you’d like to learn more about our experience and approach, visit our About page. When you’re ready to discuss your housing goals, get in touch with us and we’ll be happy to help you explore the right path.